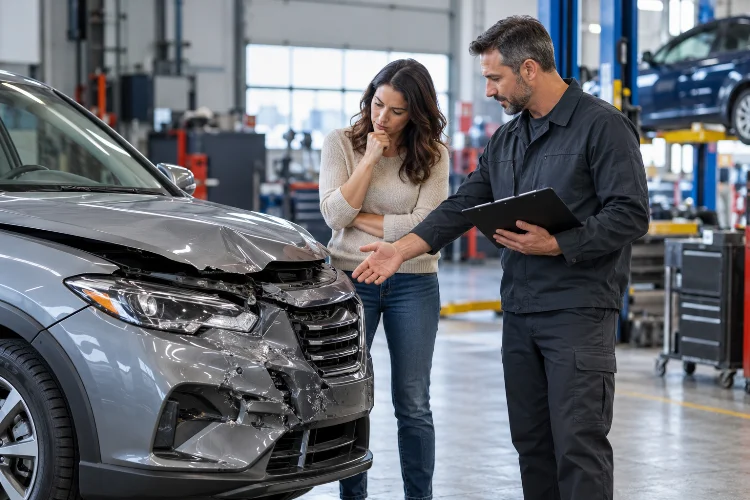
Imagine getting into a car accident that leaves your front bumper cracked, one headlight broken, and your hood slightly misaligned.
You take your vehicle to a repair shop, and the mechanic estimates that fixing everything will cost around $4,500.
Then your insurance company sends an initial settlement estimate of just $2,900.
That’s a pretty frustrating difference, right?
Before assuming someone made a mistake, it’s worth understanding that auto insurance repair estimates aren’t always as straightforward as they appear.
Insurance adjusters, collision repair specialists, and vehicle owners sometimes evaluate damage from different perspectives. Each may consider labor costs, replacement parts, hidden damage, and repair procedures differently.
Understanding how repair estimates influence auto insurance claim settlements can help you navigate these situations with much greater confidence.
A detailed estimate doesn’t simply describe the damage. It also helps determine the amount an insurer may approve, whether additional inspections are necessary, and whether repairing the vehicle makes financial sense.
In this guide, we’ll break down the estimating process, explain why settlement amounts sometimes differ from repair shop quotes, and explore practical ways to protect your financial interests after an accident.
1. Why Repair Estimates Matter in Auto Insurance Settlements
When an insurance claim involves vehicle damage, the repair estimate becomes one of the most important documents in the entire process.
It provides a preliminary financial picture of what restoring the damaged vehicle might require.
However, that estimate isn’t necessarily the final amount the insurance company will pay.
The Connection Between Repair Costs and Claim Payments
A repair estimate typically identifies damaged components, replacement parts, required labor, refinishing operations, and other necessary procedures.
The insurance adjuster evaluates this information alongside the policy’s coverage terms and the available accident evidence.
According to the National Association of Insurance Commissioners (NAIC), claims adjusters investigate reported losses, assess damage, and help determine appropriate insurance payments.
For example, suppose your vehicle suffers $5,000 in covered collision damage.
If your policy includes a $500 deductible, the insurer might pay $4,500 toward the approved repair costs.
This simplified calculation assumes all expenses are eligible and no additional policy restrictions apply.
The final payment may change if the repair estimate is revised or the insurer identifies exclusions, unrelated damage, or other relevant circumstances.
Initial Estimates Aren’t Always Final Settlements
Here’s something worth remembering: the first insurance estimate is often just the starting point.
A claims adjuster might inspect a damaged bumper without removing it from the vehicle.
Later, the repair shop could discover structural damage or broken electronic components behind the bumper.
That additional information may justify a revised estimate.
The California Department of Insurance explains that repair facilities can contact insurers for approval when additional accident-related damage is discovered.
This is why receiving an initial estimate doesn’t automatically mean every potential repair expense has been evaluated.
2. How Insurance Adjusters Calculate Vehicle Repair Costs
Insurance companies typically rely on specialized estimating systems, repair databases, and professional assessments when calculating vehicle damage.
These resources help organize repair operations and assign estimated costs.
Still, the final figures depend on the vehicle, damage severity, local repair market, and applicable repair procedures.
Labor Rates and Repair Time
Labor expenses are a major part of many collision repair estimates.
Bodywork, mechanical repairs, refinishing, diagnostics, and specialized electronic repairs can involve different hourly rates.
Some estimating systems calculate expected repair hours based on standardized procedures and vehicle-specific information.
For example, replacing a damaged fender might require several hours of bodywork, additional paint labor, and time for removing related components.
A repair estimate generally multiplies the applicable labor hours by the relevant labor rates.
However, the amount a repair shop charges may differ from what the insurer initially considers reasonable.
This difference can become a major factor in settlement negotiations.
Replacement Parts and Materials
The next major expense involves replacement components.
A damaged bumper might require a bumper cover, mounting brackets, reinforcement components, paint materials, and related fasteners.
Insurance estimates may include original equipment manufacturer parts, aftermarket replacements, or suitable recycled components.
The Federal Trade Commission’s Auto Repair Basics guide explains the differences among new, remanufactured, reconditioned, and salvage parts.
Each category can have different pricing, warranty conditions, and availability.
Example of an Auto Repair Estimate
Consider a hypothetical front-end collision involving a modern family SUV.
| Repair Item | Estimated Cost |
|---|---|
| Front bumper and mounting components | $650 |
| Headlight replacement | $720 |
| Body repair labor | $800 |
| Paint labor and materials | $650 |
| Sensor diagnostics and calibration | $480 |
| Additional components and fasteners | $200 |
| Total Repair Estimate | $3,500 |
With a $500 collision deductible, the insurer’s initial payment could be approximately $3,000, assuming the entire estimate is approved.
This example illustrates how individual repair items contribute to the overall settlement calculation.
Actual estimates can vary considerably depending on the vehicle and repair circumstances.
3. Why Repair Shop Estimates and Insurance Estimates Differ
One of the most common frustrations during an auto insurance claim is discovering that the repair facility and insurer disagree about the expected cost.
The repair shop might quote $6,000 while the insurer initially approves $4,700.
That doesn’t automatically mean the repair shop is overcharging or the insurer is underpaying.
Several factors can create legitimate differences.
Different Labor Pricing Assumptions
Repair shops establish labor rates based on business expenses, technician expertise, equipment investments, and local market conditions.
Insurance companies may evaluate whether those charges align with applicable standards and reasonable local costs.
A specialized collision facility might charge more because it uses manufacturer-approved procedures or sophisticated repair equipment.
An insurer may initially estimate the work using a different labor rate.
When that happens, both parties may need to review the specific repair operations and supporting documentation.
OEM vs. Aftermarket Parts
Replacement part selection can significantly influence the final repair bill.
OEM components are supplied by or for the vehicle manufacturer, while aftermarket parts are produced by other companies.
Some aftermarket components cost less, but suitability depends on the specific part, vehicle, safety considerations, and applicable requirements.
According to the Maine Bureau of Insurance, insurers may estimate repairs using OEM, aftermarket, or equivalent used parts under applicable rules.
Drivers may prefer OEM components, but the insurer isn’t automatically required to pay the additional expense in every situation.
Policy provisions, state regulations, warranties, and manufacturer repair requirements all matter.
Comparing Repair Estimates Properly
When evaluating two estimates, don’t focus exclusively on the final price.
Examine the actual repair operations, parts descriptions, labor hours, material charges, and diagnostic procedures.
A cheaper estimate may simply omit work that another repair facility considers neccessary.
Alternatively, a higher estimate might include operations that haven’t been adequately supported.
A detailed comparision helps identify the real reasons behind the pricing difference.
4. How Hidden Damage Changes Insurance Settlement Amounts
One of the biggest reasons initial repair estimates change is hidden damage.
Vehicle body panels can conceal expensive structural, mechanical, and electronic components.
Until technicians remove damaged parts, they may not know the complete extent of the repairs.
What Is a Supplemental Repair Estimate?
A supplemental estimate documents additional damage or repair operations discovered after the initial assessment.
For example, imagine a collision that leaves the rear bumper visibly cracked.
The insurer initially estimates $1,800 for replacement and refinishing.
Once the repair shop removes the bumper, technicians discover a damaged reinforcement bar, broken parking sensors, and bent mounting brackets.
The shop prepares a supplement requesting additional repair authorization.
If the newly documented expenses are accepted, the total approved repair amount may increase substantially.
The Maine Bureau of Insurance confirms that supplemental claims are common when previously concealed damage becomes visible during the repair process.
How Supplements Affect the Final Payment
Suppose the insurer initially approves $2,400 in repairs.
After disassembly, the repair shop documents another $1,100 in accident-related damage.
If the additional work is approved, the total estimated repair cost becomes $3,500.
Under a policy with a $500 collision deductible, the insurer’s total contribution would generally be $3,000.
The deductible typically applies once to the covered loss, rather than being charged again for each supplemental estimate.
However, a supplement still requires appropriate documentation and approval.
Not every additional repair request automatically qualifies for insurance payment.
Why Communication Matters
Repair facilities should notify the insurer promptly when additional damage is discovered.
Delays in submitting photographs, diagnostic reports, or updated estimates can affect the repair schedule.
As the vehicle owner, you should understand whether additional repairs have been authorized before the shop proceeds.
Clear communication can prevent unexpected costs and reduce disagreements at the end of the claim.
5. How Modern Vehicle Technology Increases Repair Estimates
Today’s vehicles contain sophisticated electronic systems that can make seemingly minor accidents surprisingly expensive.
A cracked bumper isn’t always just a plastic replacement problem anymore.
It may also involve hidden sensors, cameras, wiring, and safety-related equipment.
Advanced Driver Assistance Systems
Modern cars frequently include features such as automatic emergency braking, blind-spot monitoring, adaptive cruise control, and lane-keeping assistance.
These systems rely on carefully positioned electronic sensors.
If a collision damages a radar unit or camera, restoring the vehicle may require replacement components, diagnostic scans, and calibration.
A 2023 AAA study found that advanced driver assistance system repairs could account for up to 37.6% of total repair costs in certain crash scenarios.
Across the vehicles studied, replacing ADAS components after minor front-end collision damage averaged approximately $1,540.
That’s a substantial expense for technology that may not be visible during the initial inspection.
Calibration and Diagnostic Procedures
Replacing damaged sensors isn’t always enough to restore their intended operation.
Some systems require precise calbration following repairs.
For example, repairing a front bumper may involve aligning radar sensors used for adaptive cruise control.
Similarly, certain windshield replacements require camera calibration.
These procedures can affect settlement estimates because they involve specialized tools, trained technicians, and additional labor.
When these operations are required for a covered repair, the repair facility should document them clearly.
Electric and Hybrid Vehicles
Electric and hybrid vehicles introduce additional considerations.
High-voltage batteries, specialized wiring, thermal management components, and electrical safety systems can require qualified technicians.
After an accident, insurers may need detailed inspections to determine whether expensive electrical components were damaged.
This doesn’t mean every electric vehicle repair is automatically more costly.
However, vehicle-specific repair procedures can influence both the estimate and the decision about whether repairs are economically practical.
6. How Repair Estimates Affect Total Loss Decisions
Sometimes an insurance claim shifts from a repair discussion to a total-loss evaluation.
This happens when repairing the vehicle is impractical or when the estimated cost meets the applicable economic or legal criteria for declaring a total loss.
The repair estimate plays a central role in that decision.
Understanding Actual Cash Value
Auto insurers commonly evaluate a vehicle’s actual cash value, often called ACV, when determining total-loss settlements.
This generally reflects the vehicle’s value immediately before the covered incident, subject to policy language and state requirements.
According to the Washington State Office of the Insurance Commissioner, insurers may use comparable vehicles and local market information when determining total-loss values.
Relevant factors can include mileage, condition, equipment, trim level, and vehicle history.
Repair Costs vs. Vehicle Value
Imagine your vehicle is worth approximately $12,000 before an accident.
The initial repair estimate reaches $9,500.
Technicians also suspect additional structural damage that could raise the total cost further.
At this point, the insurer may consider declaring the vehicle a total loss instead of authorizing repairs.
However, there isn’t a single universal total-loss percentage used across the United States.
Requirements vary by state, and insurers may consider repair expenses, salvage value, and other applicable factors.
Why a Higher Estimate Can Change the Settlement
An increase in the repair estimate doesn’t always mean you’ll receive more money for repairs.
Instead, it may lead the insurer to declare the vehicle a total loss.
If the vehicle’s covered actual cash value is $12,000 and your deductible is $750, a simplified settlement might be $11,250.
The final amount may also involve applicable taxes, fees, salvage deductions, lender interests, and other adjustments.
This is why understanding the difference between repair-cost estimates and total-loss valuations is so important.
A higher repair estimate can change the entire claims resolution process.
7. How Deductibles and Coverage Terms Affect Settlement Payments
Even an accurate repair estimate doesn’t tell you exactly how much money you’ll receive.
Insurance policies contain deductibles, coverage limitations, exclusions, and other conditions that influence payments.
These provisions must be considered alongside the cost of restoring the vehicle.
Deductibles Reduce Certain Claim Payments
Suppose an adjuster approves $4,200 in covered collision repairs.
With a $500 deductible, the insurer would generally contribute $3,700.
With a $1,000 deductible, the contribution would generally fall to $3,200.
The repair estimate hasn’t changed, but the policyholder’s share has.
This is why it’s important to distinguish the total repair cost from the actual insurance payment.
For claims against another driver’s liability insurance, the deductible arrangements may differ from those under your own collision policy.
Policy Exclusions and Unrelated Damage
Insurance companies typically evaluate whether claimed damage resulted from the reported incident.
For example, a collision policy may cover a newly damaged suspension component caused by the accident.
However, it generally won’t pay to replace worn brake pads merely because the car is already in the repair shop.
Pre-existing damage, mechanical failures, and normal wear may also be excluded from particular claims.
In some circumstances, replacing an older component with a new one may raise a betterment issue, potentially affecting payment under applicable rules.
The Maine Bureau of Insurance’s Auto Claims FAQs explains how betterment and replacement parts can affect claim calculations.
Diminished Value Isn’t the Same as Repair Cost
Another issue involves diminished value.
Even after a vehicle is properly repaired, its market value may be lower because of its accident history.
That potential reduction is separate from the physical repair estimate.
Whether diminished value is recoverable depends on the claim circumstances, applicable law, and policy terms.
It is not automatically included in every collision settlement.
8. What to Do When Your Insurance Settlement Seems Too Low
Receiving an estimate significantly below the repair shop’s quote can be stressful.
Fortunately, you can ask questions, provide additional evidence, and seek clarification before accepting a disputed settlement.
The key is approaching the situation with accurate documentation rather than assumptions.
Request an Itemized Estimate
Start by asking the adjuster for a detailed breakdown of the proposed repair costs.
Check the labor hours, parts selection, paint materials, diagnostic procedures, and any omitted operations.
If something appears incorrect, identify the specific line item.
For example, perhaps the repair facility recommends replacing a damaged structural support, but that component isn’t included in the insurer’s estimate.
Ask the shop to explain the need for replacement and provide supporting photographs or technical documentation.
This makes the disagreement easier to evaluate.
Obtain a Second Repair Opinion
If the dispute remains unresolved, consider consulting another qualified repair facility.
The Federal Trade Commission recommends considering second opinions for expensive or complicated repairs.
A second estimate may provide useful information about labor requirements, replacement parts, or overlooked damage.
However, a higher quote alone doesn’t guarantee a larger settlement.
The supporting repair procedures and their connection to the covered loss still matter.
Understand Your Repair Shop Rights
In many U.S. jurisdictions, vehicle owners may select their preferred repair facility.
Insurers may recommend network repair shops, but the rules governing shop selection and reasonable repair costs vary by state.
For example, California has specific consumer protections regarding repair shop choice and insurer payment obligations.
Before authorizing work, confirm which expenses the insurer has approved and whether the chosen repair facility expects any additional payment from you.
Escalate Disagreements Professionally
If you believe an estimate remains inaccurate, request a written explanation from the insurer.
Ask whether a supervisor can review the disputed items or whether the policy includes an appraisal provision applicable to the disagreement.
The NAIC advises consumers to document communications and contact their state insurance department when claims concerns remain unresolved.
Keep in mind that appraisal provisions and dispute procedures vary.
The insurer’s initial decision isn’t necessarily the final word, but successfully challenging it usually requires credible supporting evidence.
9. Practical Ways to Improve Your Claim Settlement Experience
Understanding the estimating process is useful, but taking the right steps after an accident can make an even bigger difference.
Good documentation makes it easier for adjusters and repair specialists to evaluate the damage accurately.
Document Everything Before Repairs Begin
Take photographs showing the entire vehicle and detailed images of damaged areas.
Keep copies of repair estimates, accident reports, diagnostic results, towing receipts, and communications with the insurer.
Also record when inspections occur and when additional repair work is requested.
These documents may become particularly important if hidden damage is discovered or if the insurer questions whether certain components were affected by the accident.
Review Every Estimate Carefully
Don’t assume a repair estimate is complete simply because it looks professional.
Ask your repair facility whether the document includes all visible damage and which components still need further inspection.
Find out whether additional diagnostics, sensor calibration, or specialized procedures may be required.
If the insurer issues an initial payment, clarify whether the claim remains open for qualifying supplements.
Some payments can be revised, while other settlement agreements may include release provisions that affect further claims.
Understanding the payment conditions before signing anything is essential.
Confirm Repairs and Final Costs
Before collecting your vehicle, review the final invoice.
Compare the completed work against the approved repair estimate and any supplemental authorizations.
Ask whether required diagnostic checks and calibrations have been completed.
You should also understand the repair facility’s warranty and whom to contact if a problem appears after the repairs.
The goal isn’t simply to secure the largest settlement possible.
It’s to make sure your vehicle receives appropriate covered repairs and that you’re not left paying unexpected expenses because of overlooked damage or unclear communication.
Repair estimates have a significant influence on auto insurance claim settlements because they establish the expected cost of restoring a damaged vehicle.
However, the final payment depends on more than the initial repair quote.
Insurance adjusters consider labor rates, replacement parts, hidden damage, repair procedures, deductibles, and policy conditions. Modern vehicle technology and total-loss calculations can further complicate the process.
Understanding these factors helps drivers recognize legitimate cost differences and identify situations where additional review may be appropriate.
Ready to take more control of your next insurance claim?
Start by documenting vehicle damage, requesting detailed repair estimates, and reviewing your insurance coverage before an accident happens.
If an offer seems inadequate, ask for an explanation and provide supporting evidence.
A more informed approach can help you secure an appropriate settlement while avoiding unnecessary confusion and financial stress.